
Ask most people whether debt is bad, and the answer will come quickly. Ask a financial adviser the same question, however, and the response is more considered.
“Debt isn’t inherently bad,” says finance coach and chartered accountant Carol Glynn. “Having debt doesn’t mean you have failed financially. What matters is the purpose behind the debt and why you’re using it.”
Steve Cronin, financial adviser and founder of Dead Simple Saving, frames his response in straightforward economic terms. “There is cheap debt like mortgages and car loans, then there is expensive debt like personal loans and credit card debt. Expensive debt is bad and can ruin your life. Cheap debt is fine and can help you get ahead in life, as long as you can afford the monthly payments.”
A mortgage sits at the better end of the spectrum for both advisers. The interest rate is typically low, and the borrowing is attached to an asset that builds equity or generates income. For UAE residents, however, the mortgage question depends on how long you’ll stay. “Buying is worth it when you plan to spend at least seven to 10 years in the country, and you value stability,” says Mr Cronin. “If you prefer flexibility of location or country, then renting is much better.”
The gap between good and damaging debt
The gap between good debt and damaging debt often comes down to basic knowledge. Ms Glynn identifies a cluster of common failures among borrowers, including not understanding interest rates or the effect debt has on their monthly income. “They don’t check their debt ratio, which is how much of their income the debt absorbs. They don’t do scenario planning to check whether they could still afford the debt if their income dropped,” she adds.

Mr Cronin says many borrowers do not even know what interest rate they are paying.
Knowing your limits matters as much as knowing your rate. The UAE has a regulatory safeguard – a debt burden ratio that caps total loan repayments at 50 per cent of monthly income – but both advisers recommend more conservative personal thresholds. Mr Cronin becomes concerned once repayments exceed 40 per cent of income.
“You could easily lose your job, face a pay cut or see your variable loan payments increase when interest rates go up,” he says. Ms Glynn’s rule for mortgage debt is 30 per cent, and she recommends holding a larger emergency fund for anyone carrying debt beyond that level.
The UAE’s particular pressures
Living in the UAE brings its own pressures. The country’s visible wealth can make certain kinds of spending feel expected.
“Lots of people appear wealthy and successful in the UAE,” says Mr Cronin. “People are attracted to the glamorous lifestyle they see around them, and they go into debt to fund it. But it’s a trap, and it makes you vulnerable if anything happens to your income.”
He also points to the supply side of the problem. “The banks are quite willing to give you loan top-ups, card limit increases and new cards, so the temptation is coming from both sides: extra spending and extra debt.”
Ms Glynn, who works with clients across several markets, says the UAE has a lifestyle expectation she doesn’t often see elsewhere. Credit is significantly easier to obtain here than in other countries, with attractive perks – points, gym memberships, travel benefits – that draw people in before they fully understand the terms, she adds. “The issue is that not everyone understands how credit cards work, so they get into credit card debt without meaning to.”
Navigating the products
Credit cards, used correctly, draw measured praise from both advisers. Ms Glynn puts all her spending on hers to accumulate points, then clears the balance in full each month. “I never pay interest, because the rates are so high they would cancel out any benefit I get from points systems.”
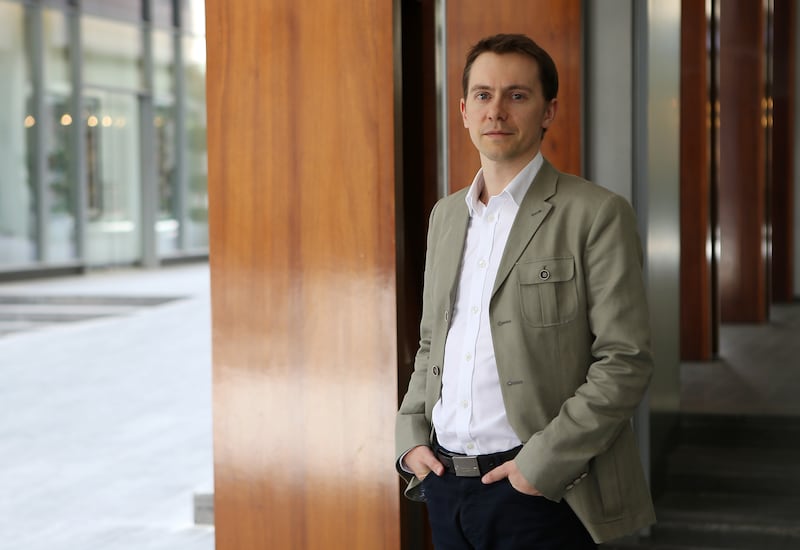
Mr Cronin agrees that credit cards are useful, offering purchase protection as well as points or cashback. But, he warns, “you must pay off your card in full each month, otherwise you’ll end up in a debt spiral”.
Buy now, pay later services – prominent in the UAE through Tabby and Tamara – draw far more caution. “You are just kicking the can down the road,” says Mr Cronin.
For Ms Glynn, they’re useful for covering a high, unexpected cost you cannot meet using cash. “Spreading that cost over a few months can help. They shouldn’t be used for everyday payments, because you lose clarity over your finances very quickly.”
Personal loans, meanwhile, draw the harshest verdicts. “I don’t recommend personal loans at all,” says Mr Cronin. Ms Glynn has one exception: consolidation – moving multiple high-rate credit card balances into a single, lower-interest structured repayment.
If you’re already worried
For anyone concerned about existing debt, both advisers begin with the same instruction: clarity first. “Write down every debt,” advises Ms Glynn. “For each credit card or loan, note how much is owed, the interest rate and the minimum monthly payment. Then rank them from most to least expensive by interest, and from lowest to highest balance.”
It is also important to be honest with yourself about why you ended up in debt, she adds. “Look at your financial habits and your money mindset. If you clear the debt without changing the behaviour behind it, you’re at high risk of building it up again and repeating the cycle.”
Mr Cronin warns that debt problems build slowly, then all at once. “Don’t allow yourself to get anywhere close to the edge: make sure you are able to save some money each month and have an emergency fund so you can be resilient against whatever life throws at you.”
The right size of emergency fund, which Ms Glynn calls a “cash cushion”, is personal, “but I would start with at least three months of living expenses”, she says. “Then decide if that would be enough to cover loss of income until you can find a new role. If not, then consider saving six months of living expenses. Keep it in a high-interest account so it is also growing in value while serving its purpose to protect you in the case of financial emergencies.”