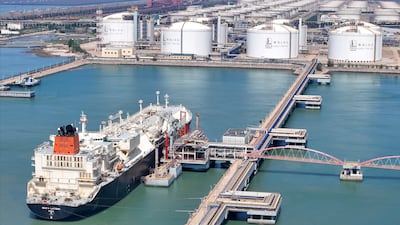

For most of this year, the conversation about liquefied natural gas (LNG) has been about scarcity: the Strait of Hormuz, force majeure, rerouted cargoes, buyers in South Asia priced out of the market. That disruption is real, and it has not gone away. But it is the wrong lens for the decade ahead.
Look past this year's headlines and the market is heading somewhere else. New liquefaction capacity on the US Gulf Coast and Qatar's North Field expansion will come on stream through the second half of this decade, and the world is widely seen as well supplied. The question for every producer, buyer, trader and terminal owner is not whether there will be gas. It is what it will take to compete when there is.
The stage before it created enormous value. Value chains unbundled, contract destination restrictions loosened and flexible portfolios were built, and a cargo loaded at Ras Laffan or in Louisiana could find its way to almost any buyer in the world. That connectivity is the industry's great achievement. It is also what the industry now has to manage. A system this interdependent does not perform simply because each of its parts does.
Abundance raises the stakes
Three things change when supply is plentiful.
First, the players become more sophisticated. Producers are buying into production facilities on other continents and becoming portfolio players. QatarEnergy is the majority owner of Golden Pass in Texas, and Adnoc, through its international arm XRG, holds equity in Rio Grande LNG. Buyers also run portfolios, traders take long-term positions, and infrastructure owners sell services they never offered before. Almost everyone is moving into an adjacent role.

Second, competition shifts from fixed positions within one chain to competition between alternative chains. Value will not simply be negotiated harder; it will be reconfigured. A role that looks secure today can be quietly bypassed by a different combination of supply, shipping, storage and finance, and the first warning is rarely dramatic: a lost customer, a missed cargo, a margin that narrows a little more each year.
Third, the system becomes more complex. "The market will provide" describes allocation, not assurance. A cargo can be available without being financeable, shippable, receivable or usable by the buyer who needs it. A portfolio of contracts can look diverse and still depend on the same route, the same terminal and the same lenders. This year, the countries most reliant on Gulf supply learnt that the hard way.
Speed with rigour
In this market, speed is part of value. Slow execution is not neutral; it hands the opportunity to whoever moves first. But speed without understanding destroys value just as surely. The advantage will belong to organisations that can decide at the pace of the market and still know exactly what they are committing to – physically, commercially and financially.
That is harder than it sounds, because most organisations were not built for it. Trading, shipping, regasification, credit and legal teams can each perform well on their own but sequential performance or reassessment misses the deal. Strong functions can still form a weak system. Flexibility written into a contract is worth very little if the ships, storage and terminal capacity behind it do not line up when it matters.
When success is the barrier
The hardest part is that the current models still work. But still working is not the same as still competitive. When a model has delivered reliably, success becomes the strongest argument against changing it, and caution starts to look like prudence.
None of this is an argument against markets, long-term contracts or specialist roles. Nor is it a call for every buyer to become a trader. The real question is whether each organisation understands its dependencies and has the capability to make its chosen model work.
For the Gulf, this matters more than most. Qatar and the UAE built their place in this industry on reliability. In September, I wrote in these pages about trust being the Gulf's most valuable export. In a well-supplied market where buyers have choices, that trust becomes the product itself. It belongs to the whole industry, not one country, and it is earned only when the complete chain delivers.
The producers, buyers and traders that do well in LNG 4.0 will be those shaping the emerging value chains, rather than accepting the role someone else hands them. The question I would put to any board is a simple one: what are you changing now, before something visibly breaks?
Pat Breen is chairman and chief executive of Gas Strategies