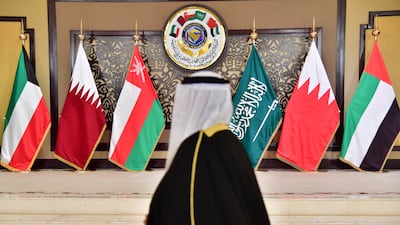

This week, ministers, manufacturers and investors from across the Gulf gather in Bahrain for the inaugural Made in GCC Forum. The discussions range from artificial intelligence and advanced manufacturing to financing, regional value chains and supply-chain resilience. Yet, perhaps the most important question is contained in the forum’s name, but what does it really mean for something to be “Made in the GCC”?
For the past two decades, Gulf countries have built increasingly ambitious national industrial strategies, and the results are visible from advanced manufacturing in the UAE and Saudi Arabia to petrochemicals in Qatar, aluminium in Bahrain and new minerals and logistics investments in Oman. However, the region is not living to its full potential, and the opportunity is to connect these strengths.
The economic case is compelling. The Gulf’s combined gross domestic product reached $2.3 trillion in 2024, which would make it the world’s ninth-largest economy if treated as one, ahead of Canada, Brazil and Russia. Its 61.5 million people generate an average GDP per capita of about $38,000. Its commercial banks hold $3.9 trillion in assets, while 13 GCC sovereign wealth funds collectively manage more than an estimated $4.5 trillion.
That is considerable economic firepower. Yet its real potential becomes clearer when we look beyond the aggregate numbers and consider what the six economies can offer one another.
Saudi Arabia brings scale: the largest domestic market, an expanding industrial base and enormous demand generated by its transformation programmes. The UAE brings world-class logistics, technology, finance, aviation and access to international markets. Qatar adds formidable gas, energy and petrochemical capabilities. Oman combines minerals and industrial land with ports facing directly onto the Arabian Sea and Indian Ocean. Bahrain has developed specialised manufacturing, particularly in aluminium, alongside a sophisticated financial sector, while Kuwait brings substantial capital, energy capabilities and one of the world’s oldest sovereign investment institutions. Put those assets together and the Gulf becomes something fundamentally different. I call this the GCC Full Potential.
Geography makes the proposition even more interesting. The Gulf sits between Asia, Africa and Europe, but unlike many economic blocs, it has maritime access in several directions. Ports on the Arabian Gulf connect it eastwards towards Asia; Saudi Arabia’s Red Sea ports provide access towards Africa, the Mediterranean and Europe; and Oman’s ports on the Arabian Sea provide direct access to the Indian Ocean without passing through the Strait of Hormuz. In a world increasingly concerned about chokepoints, supply-chain disruption and geopolitical risk, this now requires an integrated investment in land transport networks.
The lesson from the disruptions of recent years should therefore not be that every Gulf country must become self-sufficient. Six countries attempting to reproduce the same factories, warehouses, data centres and strategic inventories would be an extraordinarily expensive definition of resilience. Resilience through integration is more powerful than resilience through duplication.
Imagine instead an industrial product whose minerals originate in Oman, whose energy-intensive components are produced in Saudi Arabia or Qatar, whose advanced manufacturing and technology are provided in the UAE or Bahrain, and which can be exported through whichever Gulf, Red Sea or Arabian Sea port provides the most resilient route to its destination. That is what “Made across the GCC” could mean.
There is evidence that this type of integration produces disproportionately large economic returns. An International Monetary Fund study based on more than 13,000 investment transactions found that more than a quarter of investment into Gulf economies already originates elsewhere in the region. More strikingly, the medium-term effect of inward cross-border investment on real non-hydrocarbon GDP was estimated to be about three times greater than that of equivalent domestic investment. Capital, in other words, becomes more productive when it crosses borders.

The same principle applies to talent. A regional industrial economy of 61.5 million people can create deeper pools of engineers, researchers, entrepreneurs and specialist workers than six separate labour markets. Infrastructure can work the same way. The Gulf has already demonstrated this principle through electricity. A regional super-grid connects the member states and allows electricity and reserve capacity to move across borders. The industrial equivalent should naturally follow. AI makes this far more achievable than it would have been a decade ago. A Gulf-wide industrial platform could map what the region imports, identify where production capacity exists, forecast demand, expose supply-chain vulnerabilities, match buyers with Gulf suppliers and reroute orders when disruption occurs. Governments would gain something close to a real-time map of the Gulf’s industrial metabolism.
The objective should not be to decide administratively that one country makes one product, and another makes something else. Markets remain better at discovering competitive advantage. Government’s role should be to make the Gulf function increasingly like one industrial marketplace through common standards, interoperable regulation, connected infrastructure, open procurement and easier movement of capital, goods, data and specialist talent.
The most important exhibits in Bahrain this week may therefore not be the products already carrying a national “Made in” label. They are the products that do not yet exist. The ones that will eventually say: Made across the GCC.